

Can the high income consumer carry the US market?

 S&P 500 +0.59% to 7,811.51 US 10-year yield +2.8 basis points to 5.261% Spot gold +1.5% to $4,194.43 an ounce DXY +0.09% to 102.23
Key data to move markets today
EU: A speech by ECB Vice President Boris Vujčić
UK: Speeches by BoE Deputy Governor for Financial Stability Sarah Breeden and MPC external member Catherine Mann
USA: A speech by Cleveland Fed President Beth Hammack. Bond markets will be closed for the Columbus Day (Indigenous Peoples' Day) Holiday
GLOBAL: IMF/World Bank annual autumn meeting
Global Macro Updates
US consumer sentiment deteriorates with future spending facing limitations. On Friday, the University of Michigan’s preliminary sentiment index declined to 46.3 from 48.1 in September. This was the third straight monthly drop and the lowest reading since May. The current conditions gauge fell to 44.7, the lowest on record, from 50.9 in the previous month. The expectations index rose to 47.3 from 46.3, the first increase since July.
Consumers expect prices to rise 4.7% over the next 12 months, up slightly from September’s 4.6% year ahead view. They also saw costs rising at an annual rate of 3.5% over the next five to 10 years. Long-run inflation expectations also stepped up from 3.4% in September to 3.5%, notably higher than their 2024 range of 2.8% to 3.2%.
Higher fuel prices continue to weigh on consumers already worried about persistent inflation and the rising cost of living. Sentiment deteriorated sharply in October among lower-income consumers and those with smaller stock portfolios. Increases in sentiment among Democrats and Republicans were offset by a decline among independents this month. This will not necessarily be good news for the President facing a tight race for who will control the Senate in the run up to the midterms on 3 November.
Another study on gasoline prices and expected consumer spending by the University of Michigan, also released on Friday, showed that consumer spending is mostly being driven by higher-income households. That report showed that just under a third of consumers expected to spend as usual in the coming year on items that have experienced large price increases, while 54% said they would cut back. About 16% of consumers said they would stop buying. When asked about what purchases consumers anticipate cutting back or delaying the most, the most common responses included food/groceries, household items including durables, car buying, eating out and vacations.
US Stock Indices
Dow Jones Industrial Average +0.83%
Nasdaq 100 +0.51%
S&P 500 +0.59%, with 9 of the 11 sectors of the S&P 500 up
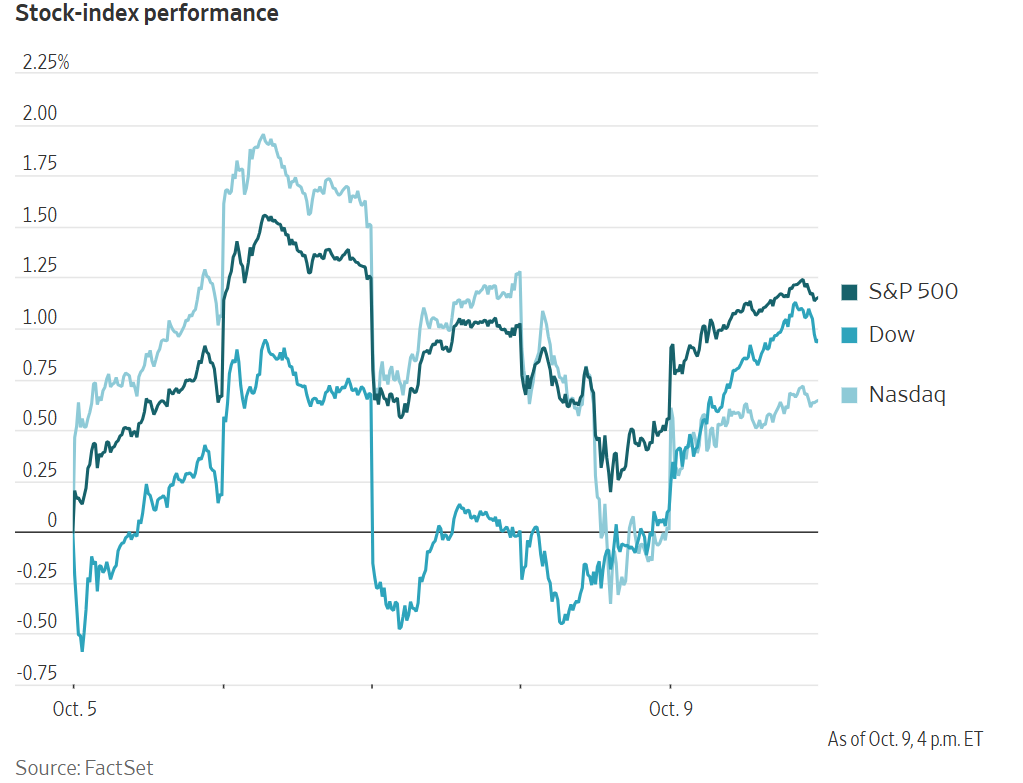
All three major US stock indices advanced on the day, logging weekly gains. The Dow Jones Industrial Average climbed 423.31 points, or +0.83%, to 51,654.95, the S&P 500 gained 46.15 points, or +0.59%, to 7,811.51 and the Nasdaq Composite rose 172.83 points, or +0.64%, to 27,366.
For the week, the S&P 500 gained +1.89%, while the Dow Jones Industrials rose +0.9%. The Nasdaq Composite was +1.84%, extending its winning streak to four weeks.
Q3 earnings season begins this week, with the big US banks and asset managers starting off the season. Wells Fargo, Goldman Sachs, Citigroup and JPMorgan Chase are all expected to report on Tuesday, while BlackRock, Bank of America and Morgan Stanley are scheduled to release their results on Wednesday.
Analysts estimate S&P 500 annual earnings growth of +30.6% for the JulySeptember period, with Energy and Technology stocks posting the largest year-on-year earnings growth of +123% and +66.5%, respectively, according to LSEG data.
In corporate news, T-Mobile US and Verizon each fell about -8% after SpaceX struck a deal to acquire a nationwide low-band spectrum portfolio.
Humana surged +12% after the US government improved its rating for the company's Medicare Advantage plans. It showed 95% of the health insurer's members were in Medicare Advantage plans rated four stars or higher for 2027.
Apple shares fell -1.1%, after Nikkei Asia reported that the iPhone maker has told some suppliers to cut production of components for its newly launched iPhone 18 Pro and iPhone 18 Pro Max, due to soaring memory chip costs and as price increases dampen consumer demand.
Deere & Co shares posted the biggest weekly decline since April 2023, due to a regulatory inquiry and lower crop prices.
Moderna shares climbed +14% after a New York Times report on a plan involving the National Institutes of Health to fast-track the development and testing of cancer vaccines.
European Stock Indices
CAC 40 +0.95%
DAX +1.13%
FTSE 100 +1.06%
Commodities
Gold spot +1.5% to $4,194.43 an ounce
Silver spot +2.46% to $60.81 an ounce
West Texas Intermediate +0.39% to $91.85 a barrel
Brent crude +0.42% to $104.72 a barrel
Gold rose on Friday for a second straight session, touching a one-week high on easing US Treasury yields and bargain buying. Spot gold was +1.5% to $4,194.43 per ounce. US gold futures for December delivery gained 1.4% to settle at $4,216.3.
Spot silver gained +2.46% to $60.81.
Oil prices rose on Friday due to the effect of Hurricane Isaias moving towards the northern Gulf of America, resulting in oil companies shutting more than 70% of crude production in US waters. Earlier in the session oil prices had dropped following President Trump stating that talks with Iran had been "productive." He also suggested that he was considering suspending the federal gasoline tax.
During the late afternoon on Friday President Trump announced on social media that he had a "highly successful" discussion with Russian President Vladimir Putin in which they agreed that Russia will immediately supply more than 300,000 metric tons of diesel to US and global markets in an effort to lower fuel prices ahead of the US midterm elections. Trump said Russia would supply another 500,000 tons in November and a further 1 million tons "immediately thereafter." President Trump said further deliveries would be “based on the condition of their diesel refineries," which have been damaged by Ukrainian attacks. The US Treasury Department issued a general license on Friday allowing importation of Russian diesel until 7 April 2027.
China, the world's top oil importer, plans to resume refined fuel exports after a brief disruption during its Golden Week holiday, also weighed on the market.
Brent crude futures settled up on Friday at $104.72 per barrel, up 44 cents or +0.42%. WTI crude futures finished at $91.85 per barrel, up 36 cents, or +0.39%.
Note: As of 4 pm EDT 9 October 2026
Currencies
EUR -0.07% to $1.1201
GBP +0.05% to $1.3231
Bitcoin +0.6% to $82,495.07
Ethereum +0.06% to $2,482.54
The dollar had its longest weekly advance since early 2025.on Friday with the DXY +0.09% to 102.23.
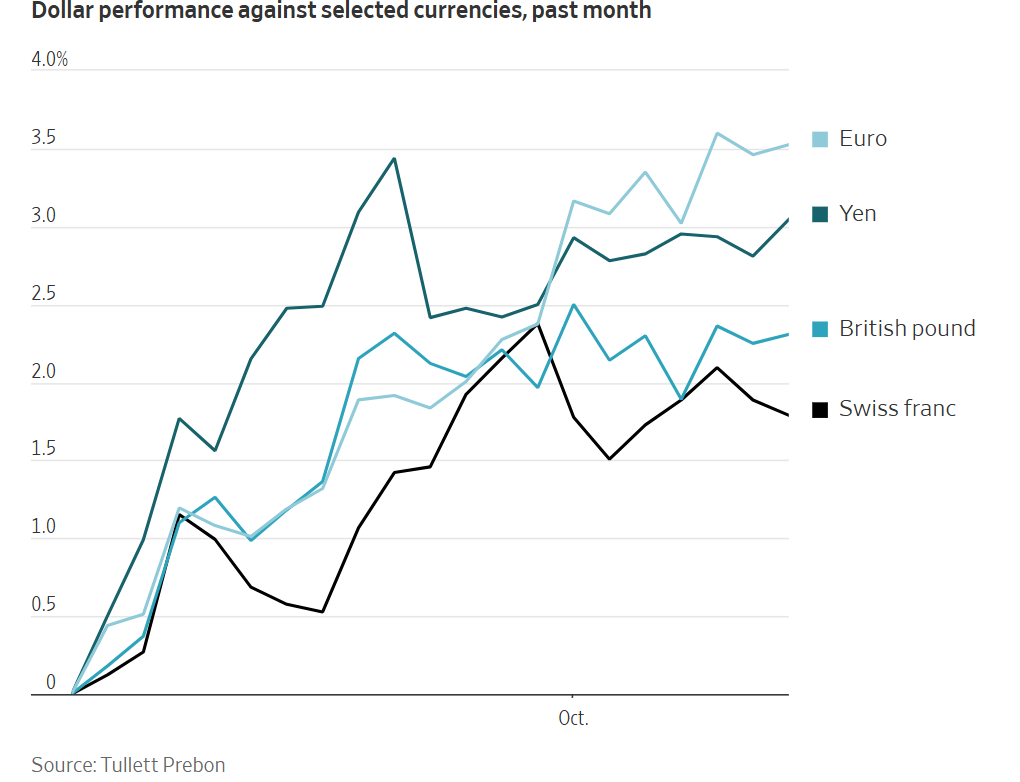
The euro slipped -0.07% on Friday, dropping for a fifth straight week as investors worried about France's record public debt.
Sterling gained +0.05% to $1.3231, but experienced its seventh straight week of declines against the US dollar, its longest stretch since November 2024.
The dollar strengthened +0.29% against the Japanese yen ¥158.31. It was the fourth straight week of weekly declines against the greenback. ff
Fixed Income
US 10-year Treasury +2.8 basis points to 5.261%
German 10-year Bund -0.8 basis points to 3.487%
UK 10-year Gilt -0.8 basis points to 5.453%
US Treasuries fell on Friday, reversing some of the gains from earlier last week. Treasury yields moved slightly higher after the University of Michigan showed that inflation expectations over the next 12 months had increased to 4.7% from 4.6% in September. Twelve-month inflation expectations have surged since 3.4% in February before the US-led war with Iran started.
The benchmark 10-year yield rose +2.8 bps to 5.261%. It was down -3.5 bps over the week, the largest weekly decline in two months. US 30-year yields were marginally higher at 5.608%, but fell -2.9 bps on a weekly basis.
On the shorter end of the curve, the 2-year yield, which typically reflects interest rate expectations, was +4.4 bps to 4.799%. On the week, the 2-year yield declined -3.4 basis points.
The yield curve flattened again on Friday with the 2s10s spread narrowing to 45.5 bps from 46.7 bps late on Thursday.
According to CME Group's FedWatch Tool, traders assigned a 82.8% probability to the Fed leaving rates unchanged at its 27 - 28 October meeting and also a 72.3% probability to a rate increase in December.
Eurozone borrowing costs fell on Friday after a sharp selloff driven by concerns about high inflation and France's weak fiscal outlook.
The premium investors demand to hold 10-year French debt over German Bunds was trading at 137 basis points,
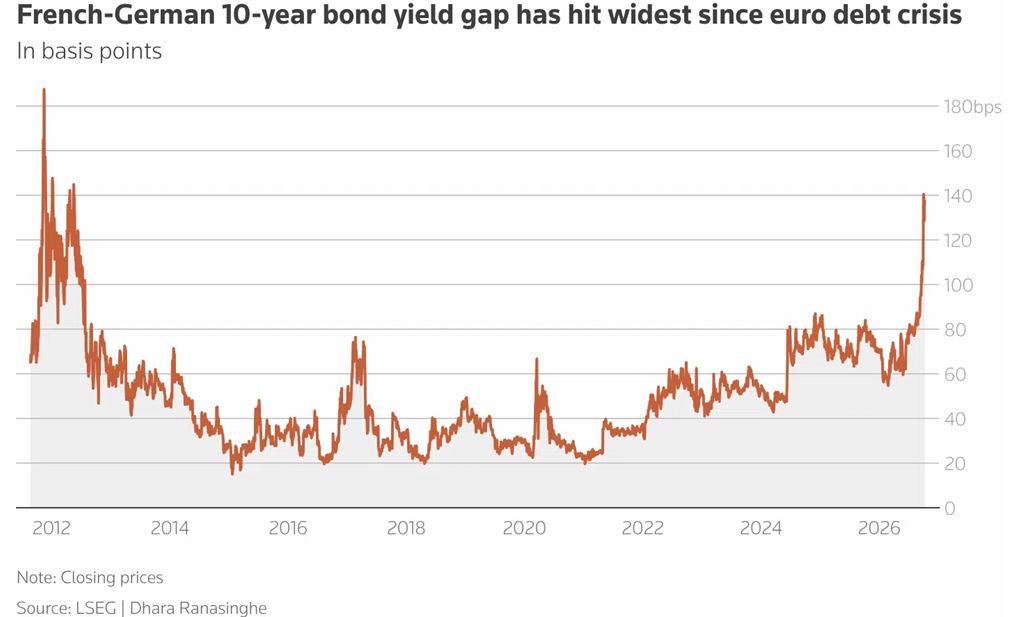
France’s 10-year OAT yield was -0.6 bps to 4.857%. Italy’s 10-year yield declined -1.9 bps to 4.571%, leaving the spread over Bunds at 108.4 bps.
The eurozone benchmark, the 10-year Bund yield, was down -0.8 basis points to 3.487%.At the long end, the 30-year yield was -0.8 bps to 3.851%.
However, the German 2-year yield, more sensitive to policy rate expectations, was +3.7 bps to 3.108%.
Money markets have scaled back bets on European Central Bank tightening, pricing the deposit rate at 2.72% by December from the current 2.50% and the policy rate at 3.20% by late 2027.
Note: As of 4 pm EDT 9 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
Ten artykuł jest publikowany wyłącznie w celach informacyjnych i nie powinien być traktowany jako oferta lub zachęta do kupna lub sprzedaży jakichkolwiek inwestycji lub powiązanych usług, do których można się tu odwołać. Obrót instrumentami finansowymi wiąże się ze znacznym ryzykiem strat i może nie być odpowiedni dla wszystkich inwestorów. Wyniki osiągnięte w przeszłości nie są wiarygodnym wskaźnikiem wyników w przyszłości.
 Wróć do wszystkich informacji


Zarejestruj się i otrzymuj informacje rynkowe
Zarejestruj się i otrzymuj
informacje
rynkowe
Subskrybuj teraz Subskrybuj teraz

Stworzone przez profesjonalistów. Dla profesjonalistów.
