

Is the Fed looking in the rear-view mirror?

 S&P 500 -0.22% to 7,801.77 US 10-year yield +0.6 basis points to 5.295% Spot gold -1.32% to $4,108.93 an ounce DXY +0.42% to 102.27
Key data to move markets today
EU: ECB Monetary Policy Meeting Accounts, German Trade Balance, Eurogroup Meeting and a speech by ECB Chief Economist Philip Lane
UK: Speeches by BoE Deputy Governor Clare Lombardelli and External Member Megan Greene
USA: Initial and Continuing Jobless Claims and speeches by Fed Governor Christopher Waller and St Louis Fed President Alberto Musalem
Global Macro Updates
Fed minutes: hawkish, but ageing fast. There was no plot twist from the September FOMC minutes. All 19 officials backed the 25 bp rate increase to 3.75% - 4.00%. Some viewed the move as insurance against supply shocks, while a more hawkish bloc saw demand-driven inflation taking hold. Most still judged another increase appropriate this year, and several considered policy only mildly restrictive.
Data arriving since the meeting have complicated the case for moving again quickly. August core PCE rose 0.2% m/o/m and 3.0% y/o/y, below expectations. July’s core PCE was revised down to 0.1% and 3.0%. Methodological changes shaved roughly 36 bps from annual core inflation, while headline PCE remained an uncomfortable 3.4%. Although Inflation looks less alarming than officials believed in mid-September, it is hardly benign.
The labour data are equally awkward. September payrolls increased by only 29,000, compared with the 90,000 consensus. Unemployment edged up to 4.2% and annual wage growth slowed to 3.0%. More importantly, earlier data weakened. The August increase was revised to 133,000 from 162,000, while July shifted to a loss of 10,000 from a gain of 21,000. The combined total for the two months was revised down by 60,000.
For investors, the revisions matter as much as the headline shortfall. The apparent hiring surge in August helped support the September rate increase, but much of that strength disappeared in September. Still, weaker employment does not ensure a dovish Fed. Officials view labour market risks as broadly balanced, inflation remains above target and resilient consumer spending indicates that demand has not capitulated.
The imbalance is clear. Weak payrolls may delay the next rate increase, but only sustained disinflation is likely to prevent it. Markets should treat the relief from the employment data cautiously and focus more closely on inflation readings, wage data and further payroll revisions. The Fed’s reaction function is placing greater emphasis on prices, while the jobs report merely bought it time.
US Stock Indices
Dow Jones Industrial Average -0.66%
Nasdaq 100 -0.21%
S&P 500 -0.22%, with 7 of the 11 sectors of the S&P 500 down
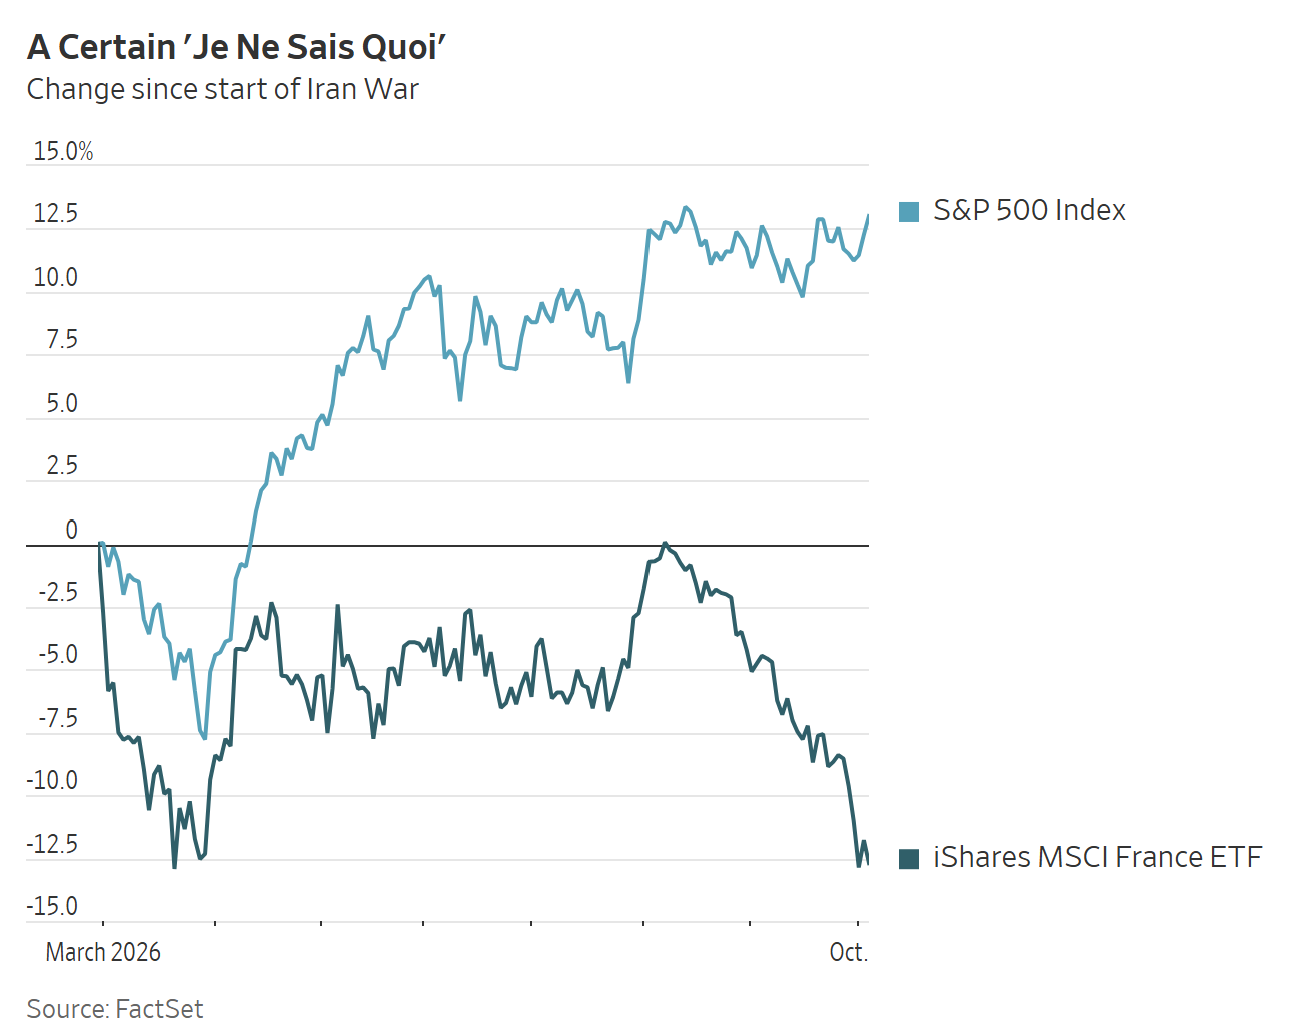
As France confronts a potential borrowing crisis and US equities remain resilient despite bond yields reaching a 25-year high, a French phrase helps explain the contrast: exorbitant privilege.
The term was coined six decades ago by Valéry Giscard d’Estaing to describe the advantage the US derives from issuing the world’s reserve currency. Even today, ‘le privilège exorbitant’ leaves US investors and consumers wealthier and less fearful than their counterparts in other developed economies.
However, major US indices retreated from record highs on Wednesday. After closing at all-time highs on Tuesday, the S&P 500 and Nasdaq Composite each fell -0.22%, while the Dow Jones Industrial Average dropped 341.41 points, or -0.66%.
In corporate news, the Financial Times reported that SpaceX is seeking $40 billion to purchase Nvidia chips, deepening the AI and rocket company’s investment in the chipmaker’s advanced technology. SpaceX plans to raise about $10 billion in bank loans and $30 billion in investment-grade debt to fund the order, according to people familiar with the matter. Apollo is expected to lead the financing and market the debt to a broad investor base, while Pimco was among a small group of lenders discussing the deal. The transaction is expected to close in 2027.
The Wall Street Journal reported that the Department of Housing and Urban Development is investigating Wells Fargo over programmes designed to expand homeownership among black Americans. In a letter to the bank, HUD asked whether the initiatives violated fair-lending laws by favouring black homeowners.
Porsche plans to raise the average selling price of its premium vehicles by 20% to €330,000 to enhance exclusivity and profitability. The automaker is also seeking to cut 5,000 jobs beyond the 3,900 positions already targeted to improve efficiency and competitiveness. By streamlining departments, reducing complexity and lowering costs, Porsche aims to bring its break-even point below 200,000 vehicles.
European Stock Indices
CAC 40 -1.22%
DAX -1.35%
FTSE 100 -0.79%
Commodities
Gold spot -1.32% to $4,108.93 an ounce
Silver spot -1.80% to $60.13 an ounce
West Texas Intermediate -1.08% to $88.94 a barrel
Brent crude -0.20% to $100.95 a barrel
Gold prices fell to a two-month low on Wednesday.
Spot gold declined -1.32% to $4,108.93 per ounce, its lowest level since 5 August.
The US dollar index rose +0.42%, making dollar-denominated gold more expensive for holders of other currencies.
Official data showed that China's central bank increased its gold purchases in September, extending its buying streak to a 23rd consecutive month.
Spot silver declined -1.80% to $60.13 per ounce.
Oil prices settled lower on Wednesday after a volatile session. The decline followed the International Energy Agency's decision to accelerate the release of oil stocks and prioritise diesel to curb record-high fuel prices as the war with Iran constrains global supplies.
Brent crude futures settled down 20 cents, or -0.20%, at $100.95 per barrel. WTI crude futures fell 97 cents, or -1.08%, to $88.94 per barrel. The WTI 2027 strip briefly traded above $80 per barrel intraday.
The IEA board said on Wednesday that the accelerated stockpile release would not include additional fuels and would instead draw from the existing 400 million barrel emergency release approved in March. The afternoon update supported ULSD's outperformance.
Yemen's Houthis attacked Aden International Airport with missiles and drones, the country's transport ministry said, as fighting intensified between the Iran-aligned group and Saudi-backed government forces.
Ukraine struck two Russian oil facilities, while Russia launched waves of missiles and drones at Ukraine, killing at least 15 people, according to Ukrainian officials.
In the US, forecasters said on Tuesday that a storm forming in the Gulf of Mexico was expected to become the first Atlantic hurricane of 2026 within two days and would likely affect oil and gas facilities.
As of 11:00 am CDT on Wednesday, the BSEE reported that 511,619 bpd of oil production had been shut in because of Tropical Storm Isaias. Natural gas shut-ins totaled 350 MMcfd.
Syria is set to provide an alternative route for Iraqi crude exports that avoids the hazardous Strait of Hormuz, with trucks being prepared to transport oil overland to a Mediterranean port. The Iraqi government asked Syria to facilitate crude exports in addition to existing fuel oil flows, Yousef Qiblawy, chief executive officer of the state-owned Syrian Petroleum, told Bloomberg news.
After the oil market closed, The Atlantic reported that the White House had asked the Pentagon to develop strike options against Iranian targets that could be exercised before the midterm elections, citing two administration officials.
Note: As of 4 pm EDT 7 October 2026
Currencies
EUR -0.57% to $1.1195
GBP -0.43% to $1.3211
Bitcoin -2.89% to $83,156.15
Ethereum -4.89% to $2,566.25
The euro fell sharply on Wednesday as renewed fiscal concerns pressured French bonds, while the dollar retained its gains following the release of minutes from the Fed's September meeting.
The euro declined -0.57% to $1.1195, approaching the 17-month lows reached on Monday.
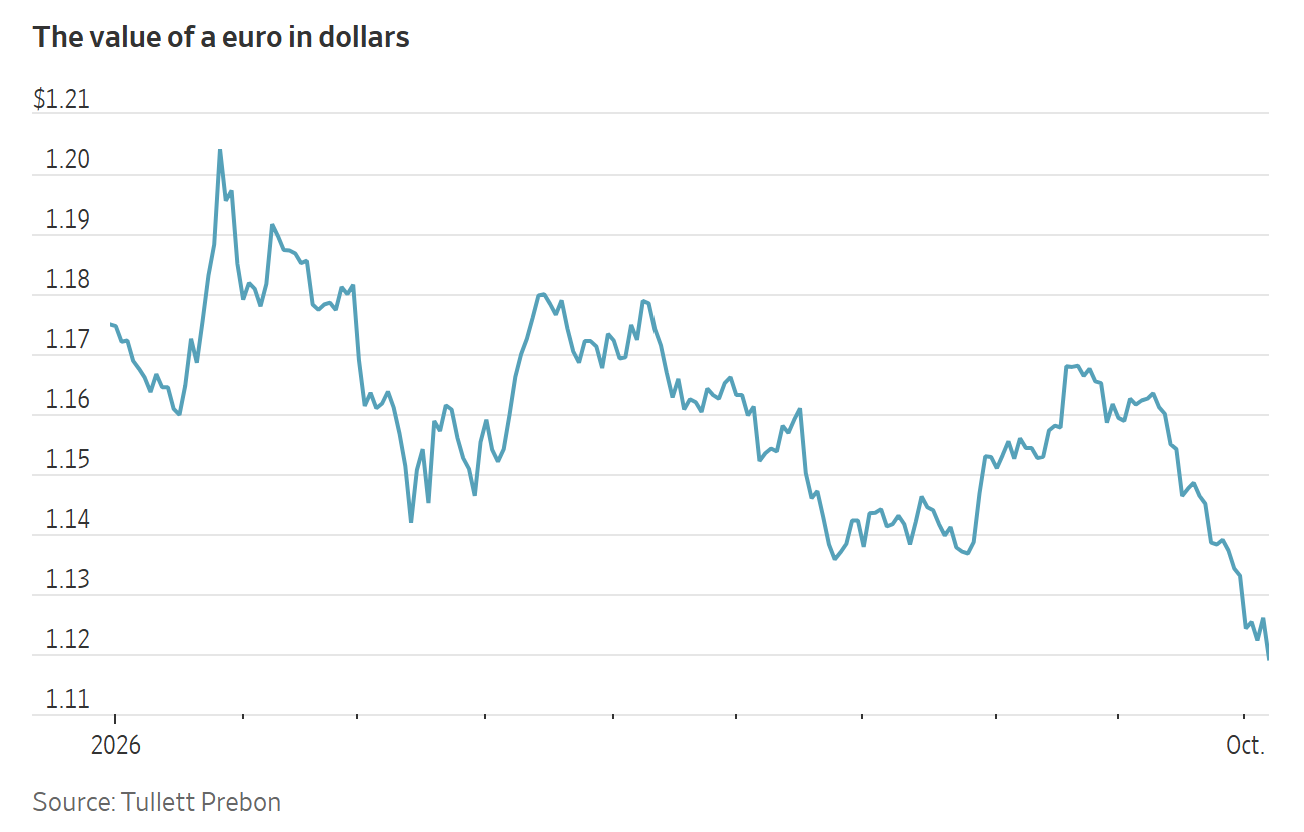
The dollar index gained +0.42% to 102.27, briefly paring its advance before recovering after the Fed minutes were released.
Sterling weakened -0.43% against the dollar to $1.3211, but rose to a 16-month high against the euro on Wednesday. The euro fell -0.27% to 84.49 pence, its lowest level since June 2025, and extending its losing streak to nine consecutive sessions.
Against the Japanese yen, the dollar slipped -0.04% to ¥158.03.
In her first press interview with Kyodo, BoJ board member Ayano Sato supported gradual policy rate adjustments, but declined to discuss the timing of the next move because of concerns about private consumption. She said those concerns underpinned her dissenting vote at the September meeting.
The article noted that Sato was one of two members who voted against the rate hike. This raised uncertainty about future moves, but suggested that her endorsement could reinvigorate the case for further tightening. Sato emphasised that rate hikes must support sustainable economic growth and said she would independently assess monetary policy's consistency with the government's expansionary fiscal stance.
Fixed Income
US 10-year Treasury +0.6 basis points to 5.295%
German 10-year Bund -0.8 basis points to 3.489%
UK 10-year Gilt +7.3 basis points to 5.454%
US Treasuries advanced in Wednesday afternoon trading, with yields retreating from session highs.
Treasury yields extended their retreat after a $39 billion auction of 10-year notes drew strong investor demand. The notes were sold at a 5.3% yield, below the level traders had anticipated before the auction.
The bid-to-cover ratio was 2.77x, above the six-auction average of 2.54x. Primary dealers received just 2.5% of the offering, their smallest share since the aftermath of the global financial crisis, indicating that investor demand was strong enough to limit dealer absorption.
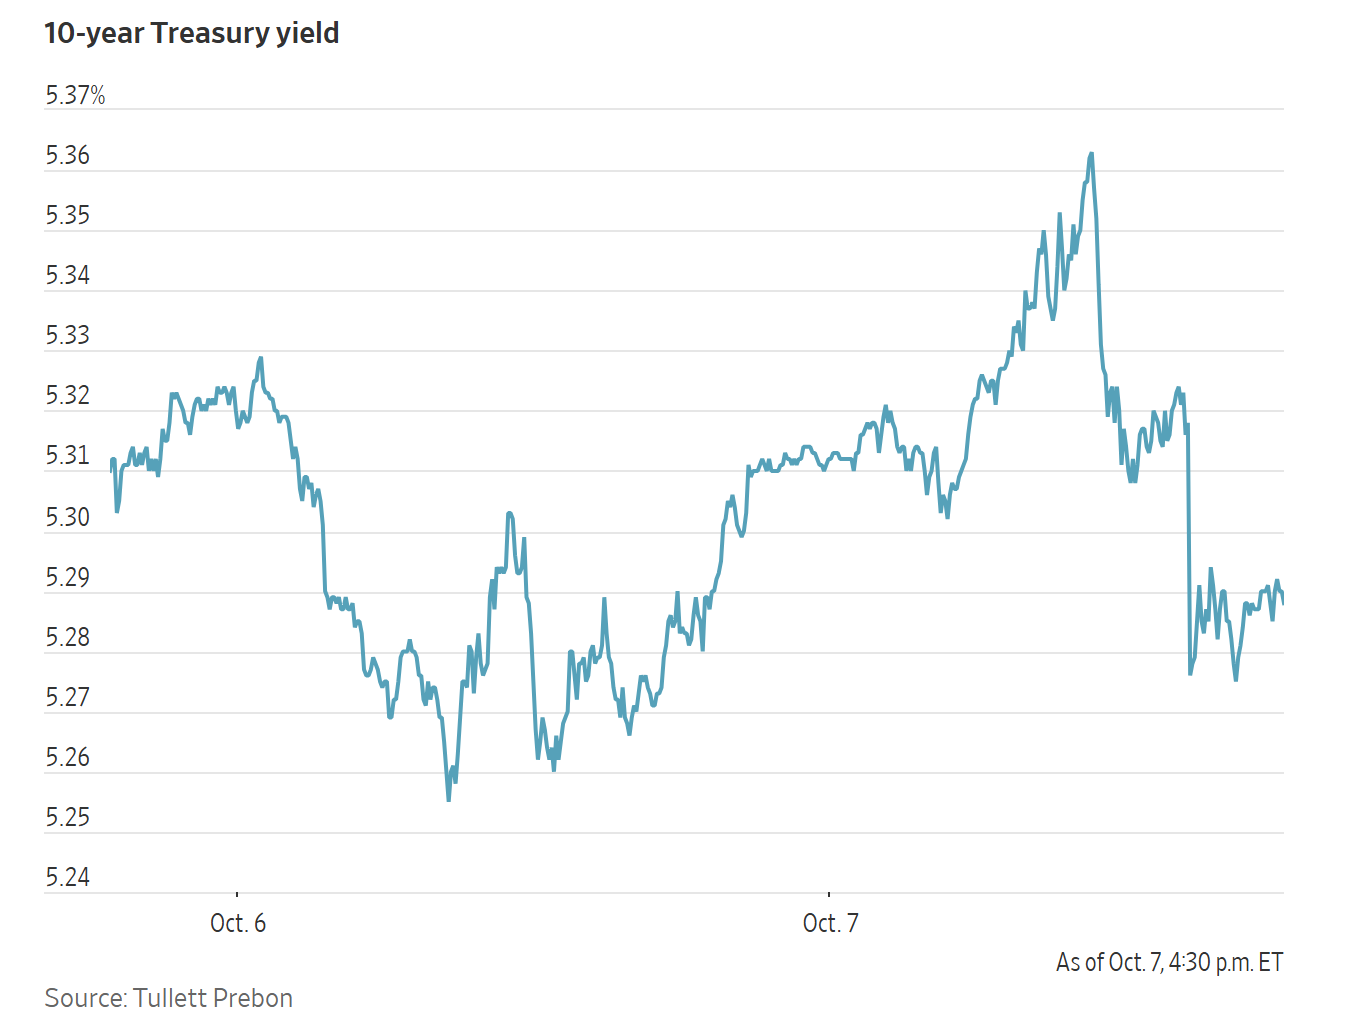
The 10-year yield closed +0.6 bps at 5.295% after reaching a 24-year high of 5.364% earlier in the session. The US 30-year yield also touched a 24-year high early in the session, but settled +1.2 bps at 5.673%.
At the shorter end of the curve, the US 2-year yield, which reflects interest rate expectations, fell -3.8 bps to 4.768%.
The US 2s10s yield curve bear-steepened by 4.4 bps to 52.7 bps.
According to CME Group's FedWatch Tool, traders assigned a 80.6% probability to the Fed leaving rates unchanged at its 27 - 28 October meeting and a 79.8% probability to a rate increase in December.
In Europe, French and Italian government bond yields rose sharply on Wednesday.
German yields remained broadly stable as investors sought safer assets, while short-dated yields declined as traders reduced expectations for ECB rate hikes.
French 10-year yields rose as much as 18.0 bps and settled +13.7 bps at 4.892%, near the 24-year high of 4.994% reached on Friday.
The spread between 10-year OAT and Bund yields widened 14.5 bps on Wednesday to 140.3 bps.
Italy's 10-year BTP yield rose +10.1 bps to 4.631%, remaining close to its highest level since October 2023.
German government debt drew safe-haven demand, with the 10-year yield down -0.8 bps at 3.489%.
Germany's 2-year Schatz yield fell -5.3 bps to 3.040%.
Traders were pricing in 55 bps of additional ECB tightening by May next year, down from approximately 75 bps a week earlier.
Note: As of 4 pm EDT 7 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
Ten artykuł jest publikowany wyłącznie w celach informacyjnych i nie powinien być traktowany jako oferta lub zachęta do kupna lub sprzedaży jakichkolwiek inwestycji lub powiązanych usług, do których można się tu odwołać. Obrót instrumentami finansowymi wiąże się ze znacznym ryzykiem strat i może nie być odpowiedni dla wszystkich inwestorów. Wyniki osiągnięte w przeszłości nie są wiarygodnym wskaźnikiem wyników w przyszłości.
 Wróć do wszystkich informacji


Zarejestruj się i otrzymuj informacje rynkowe
Zarejestruj się i otrzymuj
informacje
rynkowe
Subskrybuj teraz Subskrybuj teraz

Stworzone przez profesjonalistów. Dla profesjonalistów.
