
When does the Fed’s patience become indulgence?

 S&P 500 +0.60% to 7,722.60 US 10-year yield +1.1 basis points to 5.003% Spot gold +1.06% to $4,059.66 an ounce DXY +0.31% to 102.35
What to look out for today
Companies reporting on Wednesday, 28th October: Alphabet, Biogen, Boston Scientific, Carvana, Chipotle Mexican Grill, eBay, Equinix, FedEx, Ford Motor, Fortinet, GE Healthcare Technologies, GE Vernova, Honeywell Aerospace, KLA, MGM Resorts International, Microsoft, Phillips 66, ServiceNow, Smurfit WestRock, T-Mobile, Vertiv Holdings
Key data to move markets today
EU: German GfK Consumer Confidence Survey
UK: Autumn Forecast Statement
USA: Fed Interest Rate Decision, Fed Monetary Policy Statement and FOMC Press Conference
Global Macro Updates
FOMC Preview. An October pause would reflect the pace of tightening, not relief from inflation. The Fed is expected to maintain its 3.75% – 4.00% range, with further tightening widely anticipated in December.
The case for raising rates is uncomfortable to dismiss. August core PCE inflation was 3%, while September’s hotter core CPI reading and AI-related shortages challenge the notion that inflation is merely an energy story. With unemployment at 4.2% and demand resilient, another hike would insure against sector-specific shocks becoming embedded in broader pricing behaviour. Uncertainty over neutral rates further weakens claims that policy is sufficiently restrictive.
Yet there are valid arguments for holding. New York Fed President John Williams told Bloomberg that subdued unit labour costs and underlying inflation measures near 2.3% still supported disinflation; September’s hike also needs time to transmit. Higher Treasury yields have already increased financing costs, illustrating how reversible that restraint can be.
The economic foundation is also less uniform than headline resilience suggests. October’s Beige Book describes spending disproportionately supported by affluent households, cautious lower-income consumers and limited employment growth. September’s minutes identify weak hiring dynamism, depressed mortgage borrowing and tighter credit for small businesses and private-credit borrowers. Further tightening could therefore squeeze the interest-sensitive economy before materially cooling the comparatively rate-insensitive AI boom. These vulnerabilities constrain the pace.
The FOMC can afford one meeting’s patience, consistent with Fed Governor Christopher Waller’s non-consecutive-hike argument, but not an open-ended exemption from disappointing inflation numbers. Anchored expectations depend on credible policy. Fed Chair Warsh is likely to keep further tightening on the table, especially if bond-market restraint eases or price pressures widen.
US Stock Indices
Dow Jones Industrial Average +0.03%
Nasdaq 100 +1.29%
S&P 500 +0.60%, with 6 of the 11 sectors of the S&P 500 up
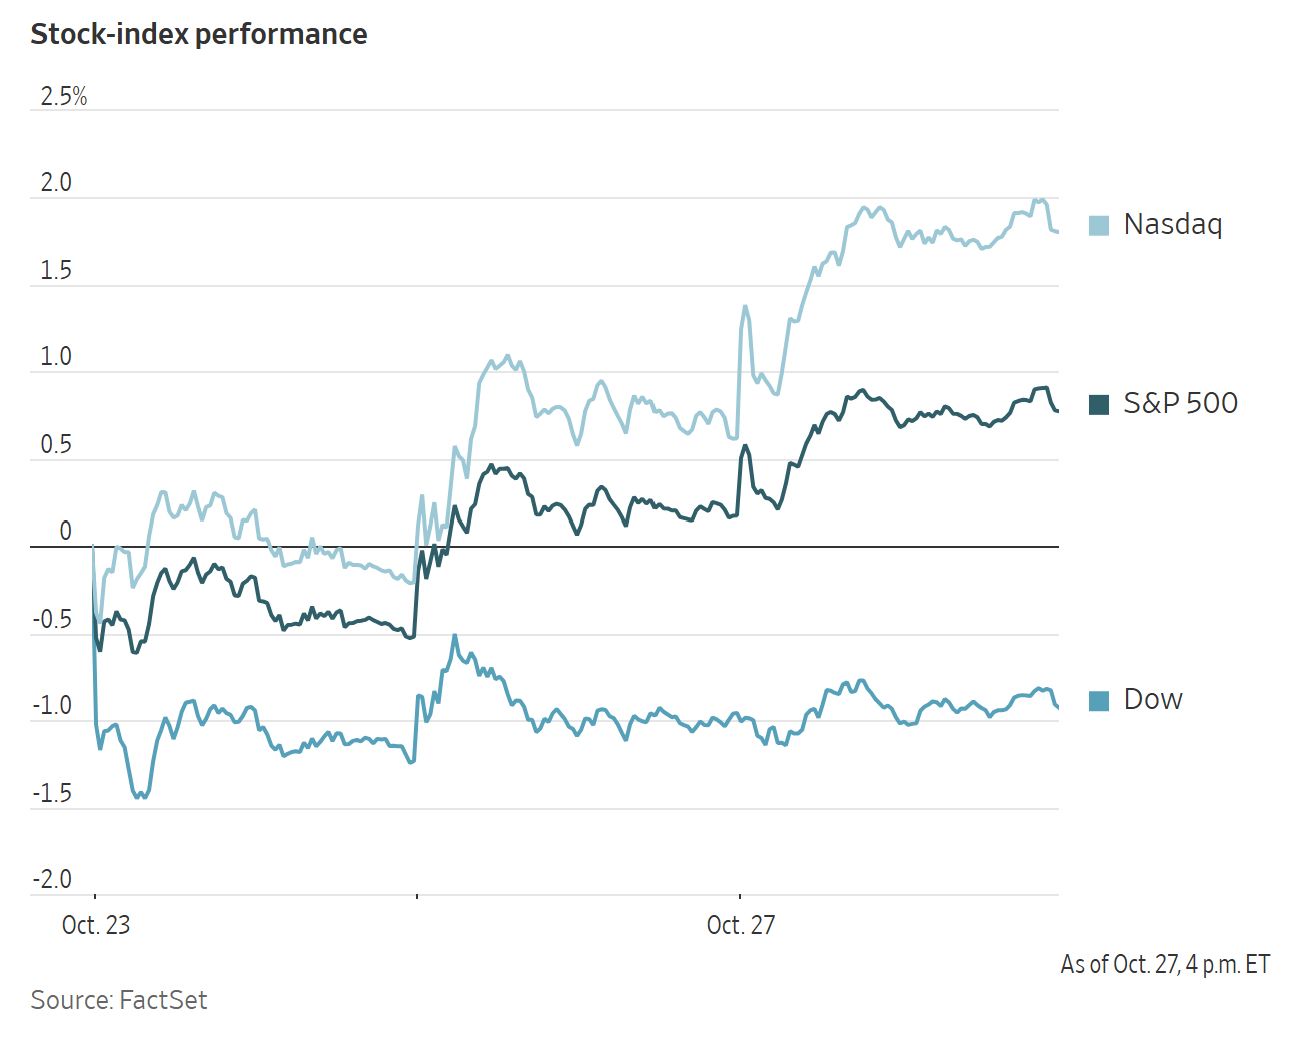
The Anthropic-driven rally continued for a second day as technology stocks lifted the Nasdaq Composite +1.18% and the Nasdaq 100 +1.29%. The Dow gained +0.03%, or 15.99 points, while the S&P 500 rose +0.60%.
In corporate news, General Motors plans to transfer its listing from the New York Stock Exchange to Nasdaq, with trading expected to begin on 17 November under its existing GM ticker. The move would position the automaker for inclusion in the Nasdaq 100, which comprises the exchange’s 100 largest nonfinancial companies.
S&P Global is considering options for its Capital IQ research platform and most of Kensho Data & Platforms, including a possible spinoff. It plans to retain RatingsDirect, RatingsXpress and Enterprise Solutions.
Oracle will offer cloud services powered by Cerebras Systems’ computers, which use giant chips spanning entire silicon wafers. Oracle Cloud Infrastructure will begin deploying the hardware in its data centres in the first half of 2027.
Corporate Earnings Reports
Posted on Tuesday, 27 October from The Pulse, our real-time AI-driven news tool. Available exclusively on the EXANTE Web Platform
American Tower reported Q3 2026 revenue of $2.79bn vs $2.76bn expected, up +2.5% y/y, and adjusted EPS of $2.87 vs $2.84 expected, up +3.2% y/y. Adjusted EBITDA reached $1.83bn vs $1.82bn expected. Segment revenue showed Data Centres rising +17.4% y/y to $313mn, Latin America up +10.4% y/y to $460mn, and Africa and APAC up +15.4% y/y to $428mn, whilst US and Canada fell -3.3% y/y to $1.3bn. For FY26, the company projected property revenue between $10.79bn and $10.87bn vs $10.69bn expected, alongside adjusted EBITDA of $7.25bn to $7.30bn. The board also approved an additional $2bn share repurchase programme. Management stated that operational momentum and disciplined capital allocation enabled raising the full-year outlook for the third time this year amid expanding demand for digital infrastructure.
Boeing reported Q3 2026 revenue of $24.19bn, up +4% y/y, beating the $23.84bn consensus, while adjusted core loss per share was -$0.34 vs -$0.21 expected. Operating cash flow rose +33% y/y to $1.5bn, and adjusted free cash flow reached $464mn. Segment revenue for Defense, Space & Security increased +15% y/y to $7.9bn, while Commercial Airplanes fell -3% y/y to $10.7bn with an operating margin of -6.5%. Total company backlog stood at $745bn. Operationally, the US Federal Aviation Administration certified the 737 MAX 10 and 737-7, and the US Navy selected Boeing to build its next-generation fighter aircraft. Management stated that the firm remains focused on safety, quality, and disciplined execution to meet its commitments.
Coca-Cola reported Q3 2026 net revenue of $13.4bn vs $12.92bn expected, up +7% y/y, alongside adjusted EPS of $0.91 vs $0.88 expected, up +11% y/y. Organic revenue grew +7% y/y, supported by global unit case volume up +5% and price/mix up +1%, whilst operating margin expanded to 33.4%. Coca-Cola raised its full-year 2026 guidance, expecting comparable EPS growth of at least +11% from a previous +9% to +10% forecast, organic revenue growth of at least +5%, and free cash flow of at least $13.0bn. In commercial developments, KFC switched its US beverage contract to Coca-Cola. The Chief Executive Officer stated that the quarterly results demonstrated sustained system momentum and reinforced confidence in full-year guidance.
United Parcel Service reported Q3 2026 revenue of $22.9bn vs $22.29bn expected, up +6.7% y/y, and adjusted EPS of $1.69 vs $1.63 expected, fell -3% y/y. By segment, US Domestic revenue rose +4.5% y/y to $14.865bn, International revenue grew +7.1% y/y to $5.007bn, and Supply Chain Solutions surged +18.2% y/y to $2.981bn. UPS raised its full-year 2026 guidance, now forecasting full-year revenue of approximately $92.6bn vs $91.79bn expected and adjusted EPS of around $7.28, whilst targeting Q4 revenue of roughly $25.7bn. GAAP figures included a $279mn net charge. Management stated that full-year financial targets were increased due to fundamental business strength, premium growth, and greater network efficiency.
S&P Global reported third-quarter 2026 revenue of $3.7bn, up +7% y/y, and adjusted EPS of $4.58 vs $4.43 expected, up +9% y/y. By segment, Indices revenue rose +20% y/y to $554mn, Market Intelligence rose +7% y/y to $1.3bn, Energy grew +6% y/y to $645mn, and Ratings increased +2% y/y to $1.3bn. Full-year 2026 adjusted EPS guidance was raised to between $17.70 and $17.95, with revenue growth projected at +7.4% to +8.4%. The company also launched a strategic review exploring the separation of Capital IQ and associated data assets, and finalised the acquisition of blockchain security firm OpenZeppelin. The chief executive noted that the firm achieved a very strong quarter driven by solid demand for benchmarks.
PayPal reported Q3 net revenue of $8.58bn vs $8.71bn expected, up +2% y/y, and adjusted EPS of $1.45 vs $1.31 expected, up +8% y/y. The company raised its full-year adjusted EPS guidance to approximately $5.60 vs $5.38 expected, while forecasting Q4 adjusted EPS of around $1.43 vs $1.35 expected. Operationally,
PayPal is cutting more than 2,000 jobs, reducing management positions by over -25%. In analyst actions, Truist Securities maintained a Hold rating and raised its price target to $58 from $53. The Chief Executive Officer stated that he was pleased with third-quarter performance and momentum across the business as the firm raised full-year non-GAAP guidance for transaction margin dollars and EPS.
Visa reported fourth-quarter FY26 results, delivering net revenue of $12.1bn vs $12.09bn expected, up +13% y/y, and adjusted EPS of $3.48 vs $3.44 expected, up +17% y/y. Processed transactions rose +10% y/y to 74.2bn vs 73.98bn expected, and cross-border volume rose +14% at constant currency. For Q1, the company projects low-double-digit net revenue growth and adjusted constant-dollar EPS growth at the low end of mid-teens. The quarterly dividend was raised by +16.4% to $0.78 per share. On the corporate front, Visa announced the acquisition of BioCatch for $2.4bn in cash, whilst crypto custody firm Fireblocks denied separate acquisition reports. The Chief Executive Officer stated that Visa delivered a milestone year with record annual net revenue of $46bn, representing its strongest organic growth in over 15 years.
Seagate Technology reported Q1 revenue of $4.2bn vs $4.14bn expected and adjusted EPS of $7.68 vs $7.42 expected, alongside free cash flow of $1.5bn. For Q2, Seagate guided revenue of $4.8bn vs $4.53bn expected and adjusted EPS of $9.20 vs $8.58 expected. Operationally, Seagate achieved an artificial intelligence storage milestone as its Mozaic HAMR and SMR drives gained Broadcom approval and completed Microsoft Azure hyperscale qualification. Regarding analyst actions, Rosenblatt Securities lowered its price target to $1100 from $1400, whilst BofA Securities maintained a Buy rating with a $1200 price target. The Chief Executive Officer stated that the firm delivered record profitability and record free cash flow supported by robust multi-year customer demand.
Waste Management reported its Q3 2026 financial results after market close, with revenue rising +6.3% y/y to $6.85bn vs $6.82bn expected. Adjusted EPS rose +9% y/y to $2.15 vs $2.18 expected, whilst adjusted operating EBITDA increased +5.8% y/y to $2.1bn. The group reaffirmed full-year 2026 guidance, projecting revenue of $26.28bn to $26.48bn vs $26.43bn expected, adjusted operating EBITDA of $8.15bn to $8.25bn, and free cash flow of $3.75bn to $3.85bn. Segment revenue included Collection and Disposal at $5.6bn and Healthcare Solutions up +3.7% y/y to $651mn. Management stated that the firm remains on track to meet its financial targets.
Robinhood reported Q3 2026 revenue up +12% y/y to $1.424bn vs $1.42bn expected, while diluted EPS was $0.51 vs $0.56 expected, impacted by $0.07 per share in unrealised venture fund losses. Net income fell -14% y/y to $476mn, and adjusted EBITDA rose +9% y/y to $808mn. Full-year 2026 adjusted operating expense guidance was lowered to $2.675bn-$2.75bn. Growth was led by event contract revenue reaching $173mn and options revenue rising +31% y/y to $399mn, offsetting crypto revenue falling -55% y/y to $120mn. The chief executive officer stated that the firm entered the fourth quarter with strong momentum. Regionally, Robinhood secured Dubai regulatory approval for Middle East expansion and partnered with Ripple to integrate RLUSD. Mizuho reiterated an Outperform rating with a $140 price target.
NXP Semiconductors reported Q3 2026 revenue of $3.79bn vs $3.76bn expected, up +19% y/y, and adjusted EPS of $4.20 vs $4.09 expected, up +35% y/y. Automotive revenue climbed up +13% y/y to $2.1bn, Industrial and IoT rose up +39% y/y to $802mn, and Communication Infrastructure increased up +54% y/y to $503mn, whilst Mobile fell -4% y/y to $411mn. The board authorised a new $5bn share buyback programme. For Q4, NXP expects revenue of $3.75bn to $3.95bn vs $3.86bn expected and adjusted EPS of $4.14 to $4.58 vs $4.32 expected. In analyst coverage, Cantor Fitzgerald reiterated an Overweight rating with a $400 price target. The Chief Executive Officer stated that performance was driven by accelerating automotive and industrial growth drivers alongside data centre infrastructure momentum.
European Stock Indices
CAC 40 +0.51%
DAX +0.71%
FTSE 100 -0.75%
Commodities
Gold spot +1.06% to $4,059.66 an ounce
Silver spot +0.84% to $54.41 an ounce
West Texas Intermediate -1.04% to $100.20 a barrel
Brent crude -0.85% to $114.22 a barrel
Gold prices advanced on Tuesday on lower oil prices amid ongoing diplomatic negotiations in the Middle East and as investors positioned themselves ahead of the FOMC policy decision today.
Spot gold rose +1.06% to $4,059.66 per ounce after reaching a session low of $3,987.14.
Spot silver gained +0.84% to $54.41 per ounce after touching its lowest level in almost a year.
Oil futures declined on Tuesday, but remained near six-month highs as disruptions to shipping in the Middle East sustained supply concerns and an agreement to end the US-led war with Iran remained elusive.
Brent crude futures settled at $114.22 per barrel, down $0.98, or -0.85%. US WTI crude fell $1.05, or -1.04%, to settle at $100.20 per barrel.
Diplomatic efforts continued as Iranian Security Council chief Mohsen Rezaei met Supreme Leader Ayatollah Mojtaba Khamenei on Tuesday, following talks a day earlier with representatives of Saudi Arabia, Turkey and Pakistan.
According to Iranian state media, Khamenei emphasised the need to pursue Iran's interests and uphold its conditions for ending the war.
State media also reported that the four countries agreed to continue discussions aimed at strengthening cooperation on peace and security.
Nevertheless, prospects for peace remained uncertain as Yemen's Iran-aligned Houthis resumed attacks on Saudi Arabia. On Tuesday, the group said it had struck the Ras Tanura oil refinery, the largest in the kingdom, with a ballistic missile.
Continued Houthi attacks and an expanding military presence in the Gulf sustained supply risks.
October has been the worst month for attacks on commercial shipping in the Strait of Hormuz and nearby waterways, according to data compiled by the Washington Institute for Near East Policy, a think tank that has tracked maritime security incidents worldwide since 2017.
Although traffic through the Strait of Hormuz has increased, vessel attacks have also risen. These risks could intensify if US naval support weakens.
Note: As of 4 pm EDT 27 October 2026
Currencies
EUR -0.45% to $1.1122
GBP -0.28% to $1.3303
Bitcoin +1.20% to $80,704.50
Ethereum +1.68% to $2,341.70
The dollar strengthened modestly against major currencies on Tuesday, including the euro, yen and sterling, as investors positioned ahead of a series of central bank policy decisions.
The dollar index gained +0.31% to 102.35. The euro declined -0.45% to $1.1122. It extended its losses slightly after the ECB's quarterly Bank Lending Survey showed that the effects of its rate increases were becoming evident.
The Fed will announce its policy decision on Wednesday, followed by the ECB on Thursday and the BoJ on Friday. All three are expected to leave rates unchanged, placing the focus on policymakers' guidance on the outlook.
The euro remained on course to be October's weakest developed-market currency. It is -1.83% MTD against the dollar, reflecting elevated energy costs and concerns over France's fiscal position.
The dollar rose +0.31% to ¥157.94 despite Japanese Finance Minister Satsuki Katayama saying the government was prepared to take decisive action in currency markets.
Sterling fell -0.28% to $1.3303. The autumn budget is due on Thursday, with growing wary of potential government borrowing increases or tax raises that could impact gilt yields. Sterling also fell in reaction to investors positioning themselves ahead of today’s Fed policy statement.
Fixed Income
US 10-year Treasury +1.1 basis points to 5.003%
German 10-year Bund -0.8 basis points to 3.375%
UK 10-year Gilt -0.4 basis points to 5.354%
US Treasury yields were mostly higher on Tuesday, trading within narrow ranges as investors assessed the outlook for further rate increases ahead of today's Fed decision.
Trading remained subdued following recent volatility and last week's rally in US bonds, which pushed yields lower.
An auction of $70 billion in 5-year Treasury notes produced mixed results. The clearing yield was slightly above the level indicated at the bidding deadline, suggesting investors required a concession to absorb the supply, although the bid-to-cover ratio improved slightly from the previous auction.
Expectations for a Fed rate increase this week have diminished amid the recent decline in yields and mixed economic data. As of Tuesday, rate futures implied a 92.8% probability of unchanged rates at today's meeting, compared with 84.5% a week earlier, according to CME’s FedWatch data. Markets nevertheless assigned a 76.3% probability to a 25 bps rate increase in December.
US durable goods data initially pushed Treasury yields higher, showing an increase in new orders for key US-manufactured capital goods in September.
The 10-year Treasury yield rose +1.1 bps to 5.003% on Tuesday. The 2-year Treasury yield, which closely tracks expectations for the Fed's policy rate, fell -0.7 bps to 4.745%. At the long end of the curve, the 30-year Treasury yield increased +1.0 bps to 5.314%.
The US 2s10s yield spread widened by 1.8 bps from Monday to 25.8 bps on Tuesday.
Eurozone sovereign bond yields were mixed on Tuesday, with German yields falling across the curve, while French yields edged higher.
The French 10-year OAT yield rose +1.3 bps to 4.922%, leaving its spread over German Bunds at 154.7 bps.
Official data showed that consumer confidence in France, the eurozone's second-largest economy, fell to its lowest level since 2013 in early October, as the country is experiencing its worst civil unrest in years.
The German 10-year Bund yield fell -0.8 bps to 3.375%, while the 2-year Schatz yield declined -2.0 bps to 3.094%. The 30-year Bund yield decreased -0.5 bps to 3.692%.
Swaps reflecting expectations for eurozone consumer inflation in one year's time remained close to 4%, twice the ECB's target and just below April's three-year high of 3.987%.
Market-based inflation expectations have continued to rise as the war with Iran has persisted.
Germany's debt agency sold approximately €3.8 billion in a reopening of a 2-year Schatz on Tuesday at an average yield of 3.08%, compared with 3.10% at the previous 2-year auction in late September. Demand strengthened, with the bid-to-cover ratio rising to 1.3x from 1.1x at the prior sale of this maturity.
The ECB is widely expected to leave monetary policy unchanged at Thursday's meeting. However, with money markets assigning a high probability to a December rate increase and fully pricing in a second increase by April, investors will scrutinise President Christine Lagarde's remarks for indications of the policy path.
Note: As of 4 pm EDT 27 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
Ten artykuł jest publikowany wyłącznie w celach informacyjnych i nie powinien być traktowany jako oferta lub zachęta do kupna lub sprzedaży jakichkolwiek inwestycji lub powiązanych usług, do których można się tu odwołać. Obrót instrumentami finansowymi wiąże się ze znacznym ryzykiem strat i może nie być odpowiedni dla wszystkich inwestorów. Wyniki osiągnięte w przeszłości nie są wiarygodnym wskaźnikiem wyników w przyszłości.
 Wróć do wszystkich informacji


Zarejestruj się i otrzymuj informacje rynkowe
Zarejestruj się i otrzymuj
informacje
rynkowe
Subskrybuj teraz Subskrybuj teraz

Stworzone przez profesjonalistów. Dla profesjonalistów.
