

Will AI destroy the job market?

 S&P 500 -0.06% to 7,807.24 German 10-year yield -0.2 basis points to 3.485% Spot gold -0.62% to $4,167.98 an ounce DXY +0.37% to 102.29
What to look out for today
Companies reporting on Tuesday, 13th October: Goldman Sachs, Citigroup, Johnson & Johnson, JPMorgan Chase, UnitedHealth Group, Wells Fargo, Domino’s Pizza
Key data to move markets today
EU: German Harmonised Index of Consumer Prices and speeches by ECB Executive Board member Frank Elderson, Bank of Spain Governor José Luis Escrivá and ECB Chief Economist Philip Lane
UK: BRC Like-for Like Retail Sales and a speech by BoE External Member Megan Greene
USA: ADP Employment Change 4-week Average, Existing Home Sales Change, Monthly Budget Statement and a speech by Fed Governor Christopher Waller
GLOBAL: IMF/World Bank annual autumn meeting
Global Macro Updates
The IMF’s AI labour market warning. On Monday, during the annual IMF/World Bank autumn meeting, IMF Managing Director Kristalina Georgieva said that although strong investment in AI infrastructure is supporting global growth at around 3%, it was also bringing a “slow-moving tsunami” that could disrupt labour markets and taxation. She urged policymakers to rethink education and act now to help society adapt.
She warned that AI was reducing demand for many human workers by taking over routine, repetitive tasks, while simultaneously resulting in an increase in low paying jobs. She said that IMF research shows that some 40% of jobs will be either augmented, downgraded or eliminated by AI, and as high as 60% in advanced economies.
She noted that there was a risk to government revenues from AI because it moves the economy toward capital and away from labour, which is traditionally the main source of tax income.
US Stock Indices
Dow Jones Industrial Average + 0.38%
Nasdaq 100 -0.71%
S&P 500 -0.06%, with 8 of the 11 sectors of the S&P 500 up
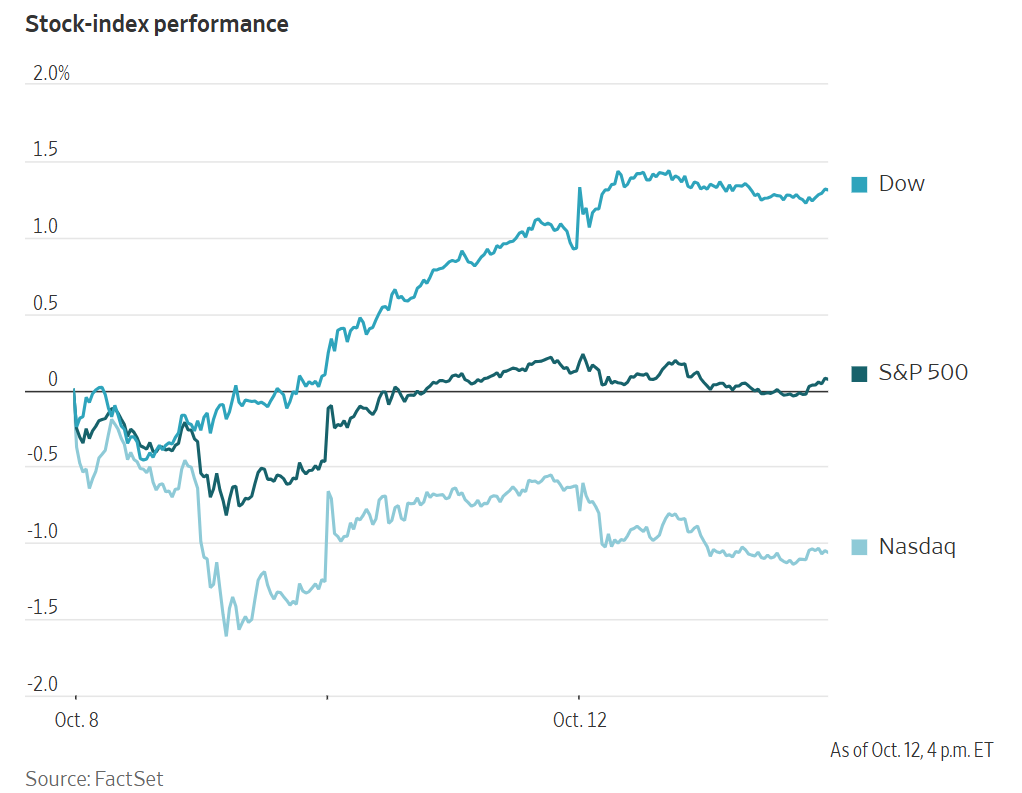
The rise in oil prices following the attacks on Riyadh over the weekend rattled markets on Monday with the Nasdaq Composite closing lower on the day. Nevertheless, Wall Street’s equity bull run experienced its fourth anniversary, with the S&P 500 up nearly 120% from its 2022 bottom. Analysts are expecting S&P 500 earnings to surge 30.6% in Q3, according to LSEG IBES data.
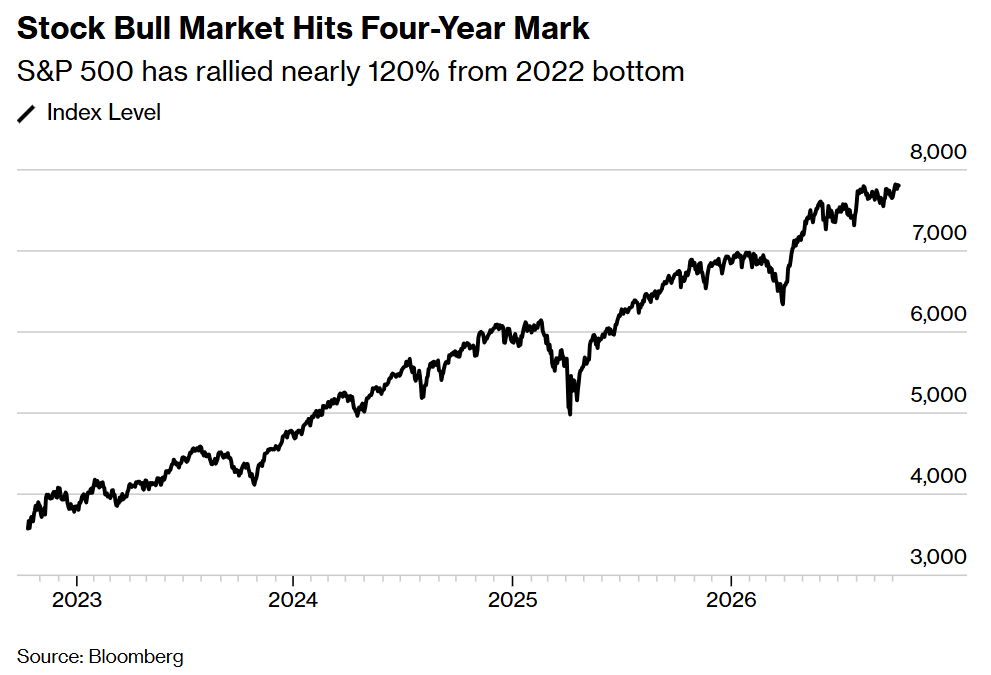
The Dow Jones Industrial Average rose 195.60 points, or +0.38%, to 51,850.55, the S&P 500 declined 4.30 points, or -0.06%, to 7,807.24 and the Nasdaq Composite fell 120.27 points, or -0.44%, to 27,245.90.
In corporate news, Chipotle Mexican Grill’s shares fell -3.8% after Starbucks said it was not buying the chain. Starbucks shares closed up +1.7%.
Microsoft’s market capitalisation climbed above $4 trillion for the first time this year after it announced plans for major deployment of its own AI chips.
Meta Platforms announced that it had released a much anticipated artificial-intelligence model as part of its multibillion-dollar push to rebuild its AI organisation.
Bristol Myers Squibb said on Monday its experimental radiopharmaceutical cancer therapy, RYZ101, which it added through its $4.1 billion takeover of RayzeBio, significantly delayed disease progression in patients with rare, advanced gastrointestinal and pancreatic tumors that had progressed after earlier treatment.
Bloomberg news reported that Epic Games has delayed the release of an upcoming video-game collaboration with Walt Disney and told its developers to use more AI tools to finish the game, according to people familiar with the project.
European Stock Indices
CAC 40 +0.38%
DAX +0.76%
FTSE 100 +0.99%
Commodities
Gold spot -0.62% to $4,167.98 an ounce
Silver spot -0.96% to $60.12 an ounce
West Texas Intermediate +2% to $93.74 a barrel
Brent crude +1.8% to $106.65 a barrel
Gold fell on Monday due to a stronger dollar. Spot gold was -0.62% to $4,167.98 per ounce.
Spot silver declined -0.96% to $60.12.
Oil prices rose on Monday as attacks on Saudi Arabia outweighed the prospect of increased supplies.
Brent crude futures settled up $1.93, or +1.8%, at $106.65 a barrel, the highest since 15 September. WTI crude settled up $1.89, or +2%, at $93.74 a barrel.
Goldman Sachs, in a note, raised its Brent price forecast for December to $90 a barrel from $85, estimating a risk premium of just over $20 a barrel. The note suggested that WTI prices would likely remain low versus Brent due to high US - Europe shipping costs and average $81 in December 2026 and $73 in 2027.
In the Gulf of Mexico, energy majors Shell, Chevron and BP were redeploying personnel and attempting to restore production at their platforms after Hurricane Isaias made landfall early on Saturday.
The Executive Director of the International Energy Agency, Fatih Birol, said all members should assess whether additional diesel releases are necessary and that countries which have not yet fully delivered pledged volumes should accelerate releases, prioritising diesel.
On Monday, Haitham Al Ghais, OPEC’s General Secretary, said that the organisation had revised down its oil demand growth forecast for this year to 400,000 barrels per day from 1.4 million bpd at the start of the year. However, he stated that OPEC expects the deferred demand to materialise in 2027.
Note: As of 4 pm EDT 12 October 2026
Currencies
EUR -0.23% to $1.1175
GBP -0.20% to $1.3206
Bitcoin -0.63% to $82.498.70
Ethereum -1.16% to $2,488.16
The dollar remained near 18-month highs on Monday, supported by safe-haven demand following the attacks over the weekend on Saudi Arabia. The DXY was up +0.37% at 102.29.
The euro was -0.23% to $1.1175 due to rising concerns around France’s fiscal deficit before the 2027 presidential election. Sterling fell -0.20% to $1.3206.
Against the Japanese yen, the dollar strengthened +0.22% to ¥158.66.
Fixed Income
German 10-year Bund -0.2 basis point to 3.485%
UK 10-year Gilt -0.2 basis points to 5.451%
US bond markets were closed on Monday in commemoration of the Columbus Day (or Indigenous Day) Holiday.
Cleveland Fed President Beth Hammack said the US central bank should move "relatively quickly" to a more restrictive monetary policy stance to fight inflation, which she feels has become more broad-based and is starting to influence firms' price-setting plans.
Investors are awaiting Wednesday’s CPI data for further indications of Fed policy and possible rate movements. Rising energy costs are expected to lift CPI by 0.6% to an annual 3.7% rate, though the core is expected to be cooler at 0.2% and 2.5% annually.
According to CME Group's FedWatch Tool, traders assigned a 78.4% probability to the Fed leaving rates unchanged at its 27 - 28 October meeting and also a 69% probability to a rate increase in December.
Eurozone borrowing costs fell slightly on Monday, but the spread between French and German borrowing costs moved higher on Monday as investors continue to worry about France’s weak fiscal position and shaky domestic policies.
The eurozone benchmark, the German 10-year yield, fell -0.2 basis point to 3.485%, while France's 10-year yield rose +3.7 bps to 4.894%. The premium investors demanded to hold 10-year French debt over German Bunds was 140.9 basis points.
Italy’s 10-year yield was -0.3 bps to 4.574%, leaving the spread over Bunds at 108.9 bps.
At the long end, the German 30-year yield was -0.7 bps to 3.844%. The German 2-year yield, more sensitive to policy rate expectations, was +2.3 bps to 3.131%.
Note: As of 4 pm EDT 12 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
Ten artykuł jest publikowany wyłącznie w celach informacyjnych i nie powinien być traktowany jako oferta lub zachęta do kupna lub sprzedaży jakichkolwiek inwestycji lub powiązanych usług, do których można się tu odwołać. Obrót instrumentami finansowymi wiąże się ze znacznym ryzykiem strat i może nie być odpowiedni dla wszystkich inwestorów. Wyniki osiągnięte w przeszłości nie są wiarygodnym wskaźnikiem wyników w przyszłości.
 Wróć do wszystkich informacji


Zarejestruj się i otrzymuj informacje rynkowe
Zarejestruj się i otrzymuj
informacje
rynkowe
Subskrybuj teraz Subskrybuj teraz

Stworzone przez profesjonalistów. Dla profesjonalistów.
